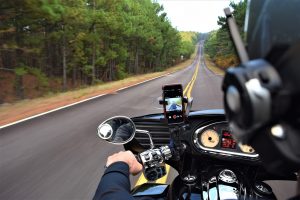
 Motorcycles have really grown in popularity across the U.S. in recent years. The Motorcycle Industry Council reports that 10.4 million American households now own a motorcycle. The reasons behind this rise in ownership vary. For younger riders, motorcycles are often a more affordable alternative to cars, while for those over 40, it’s often a luxury purchase—a fun way to enjoy the open road.
If you’re in New Bedford, and thinking about buying a motorcycle or already owning one, you’re probably aware that insurance is a must. The cost of motorcycle insurance depends on several factors, such as the type of bike you own and state laws. But beyond just having a policy, it’s crucial to make sure your coverage is comprehensive enough to protect you from the various risks that come with riding.
Before you settle on an insurance policy, here are four key coverages every motorcycle owner in New Bedford should consider:
1. Liability Insurance
Liability insurance is the foundation of your motorcycle insurance policy. It covers you if you’re found at fault in an accident that causes damage to someone else’s property or results in injury. This coverage helps pay for damages, medical bills, and even lost wages for the other party involved.
However, keep in mind that liability insurance has a limit—your insurer will only pay up to the amount stated in your policy. If the costs exceed your coverage limit, you’ll be responsible for paying the difference out of pocket. That’s why it’s a good idea to opt for as much liability coverage as you can afford. Motorcycle accidents can get costly, and having higher limits can save you from financial strain down the road.
2. Underinsured/Uninsured Motorist Coverage
Unfortunately, not everyone on the road carries enough insurance—or any insurance at all. That’s where underinsured/uninsured motorist coverage comes in. This type of insurance kicks in to protect you and your passenger if you’re involved in an accident with someone who either doesn’t have enough insurance or has no coverage at all.
This coverage can be a lifesaver, especially considering how vulnerable motorcycle riders are in collisions compared to those in cars.
3. Collision Coverage
If you’ve recently bought a new motorcycle or plan to, collision coverage is essential. In fact, if you’re financing your bike, lenders often require it. Collision insurance covers repairs or replacement costs for your motorcycle if it’s damaged in an accident, regardless of fault.
Additionally, you might want to consider comprehensive coverage, which protects your bike against non-collision incidents like theft, vandalism, or damage from fire. In a city like New Bedford, where theft rates can be high, comprehensive coverage can offer much-needed peace of mind.
4. Medical Payments Coverage
Medical payment coverage, or MedPay, is an optional but valuable addition to your policy. It helps cover medical expenses for both you and your passenger in the event of an accident. This coverage is especially useful if you have a high-deductible health insurance plan or limited medical coverage.
Even if you feel your health insurance is sufficient, it’s worth considering MedPay. Motorcycle accidents can result in significant medical expenses, and having that extra coverage could mean the difference between getting the care you need and facing unexpected out-of-pocket costs.
What’s Your Motorcycle Accident Claim Worth?
Now that you’ve got the right coverage, you might be wondering: How much would a motorcycle accident claim be worth if something happens? Several factors play into this, such as the extent of injuries and property damage, and most importantly, who’s found liable for the accident.
Liability and Damages
Liability determines who was responsible for the accident. If you can prove that the other party was at fault, the value of your claim increases. However, keep in mind that the burden of proof lies with you. If you can’t demonstrate that the other person was responsible, they’re not obligated to pay for your damages.
Damages refer to both the physical injuries and the financial losses you suffer, like medical bills, repairs to your bike, and lost wages. For example, if you were rear-ended while stopped at a red light but didn’t suffer any injuries and your bike wasn’t damaged, your case might not be worth much. On the flip side, if you sustained severe injuries and the other driver was negligent, your claim could be worth a lot more.
Can You Recover More Than the Insurance Policy Limits?
Here’s where it gets tricky. In many cases, insurance companies will offer a settlement, which is often lower than what you might get if you went to trial. However, trials carry risks, and there’s no guarantee you’ll win. While most people opt to settle, it’s important not to dismiss going to trial if you feel the insurance company isn’t offering a fair amount.
Why You Should Consult a Motorcycle Accident Lawyer in New Bedford
If you’ve been in a motorcycle accident in New Bedford, having the right coverage is just one part of the equation. You also need the right legal help to ensure you’re compensated fairly for your injuries and damages. A New Bedford motorcycle accident lawyer can help you calculate what your claim is worth—including future lost wages and earning potential—and will fight on your behalf to make sure you get what you deserve.