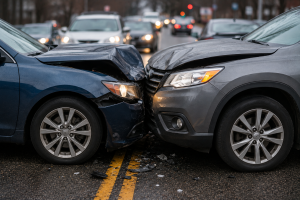
 For 37 years, Massachusetts required drivers to carry the same minimum liability coverage: $20,000 per person and $40,000 per accident in bodily injury coverage. On July 1, 2025, that changed. The state raised its mandatory minimums for the first time since Ronald Reagan was in his second term, and the new numbers, $25,000 per person and $50,000 per accident, represent a meaningful shift in the baseline coverage available to people hurt in accidents across the state, including in Fall River.
If you’ve been injured in a car accident since July 2025, this change may affect what’s available to compensate you. A personal injury lawyer in Fall River will factor current coverage requirements into every case, but understanding the landscape yourself helps you ask the right questions.
What the New Minimums Actually Mean for Injured People
The bodily injury liability coverage on an auto policy is the money that pays people the policyholder injures in an accident. When someone hits you and their insurer offers you a settlement, it’s coming out of this coverage. For 37 years, the floor for that coverage was $20,000 per person. That number had not kept pace with inflation, rising medical costs, or the reality of what serious injuries actually cost to treat.
The increase to $25,000 per person doesn’t solve the problem of underinsurance in serious injury cases, but it does raise the baseline. For minor to moderate injury cases where the damages fall within policy limits, having a higher minimum means a larger pool is available without needing to pursue underinsured motorist claims or other sources.
It also matters in the context of uninsured motorist coverage, which Massachusetts requires and which mirrors your liability limits. A driver who carries only minimum UM coverage now has $25,000 per person available rather than $20,000 if they’re hit by an uninsured or underinsured driver. That gap matters in crashes where the other driver has fled or has no insurance.
Why Minimum Coverage Is Still Often Not Enough
The honest reality is that even the new minimums can fall well short of what a serious injury actually costs. A single emergency room visit, ambulance transport, and overnight hospital stay can exceed $25,000 before any surgery, rehabilitation, or specialist care is added. For injuries that require surgery, extended physical therapy, or long-term treatment, the total medical costs can reach multiples of the minimum policy limit.
When the at-fault driver carries only minimum coverage and your damages are significantly higher, this is where underinsured motorist coverage becomes critical. Massachusetts does not require UIM coverage, meaning drivers can decline it. If you have it on your own policy, it fills the gap between what the at-fault driver’s insurer pays and your actual damages up to your UIM limit. If you don’t have it, and the at-fault driver’s policy is exhausted, recovering the remainder of your losses becomes significantly harder.
This is worth knowing as a general principle: having robust UIM coverage on your own policy is one of the most effective things you can do to protect yourself financially in the event of a serious accident. It’s relatively inexpensive compared to the protection it provides, and it covers situations that are entirely outside your control.
What This Means for Cases Where Multiple People Were Hurt
The per-accident limit matters in crashes that injure more than one person. Under the new minimums, a policy that covers $50,000 per accident can be divided among multiple claimants. If three people were seriously injured in a crash caused by a driver carrying minimum limits, all three are competing for that $50,000 combined maximum. In that scenario, no single person gets the full $25,000 per-person limit.
Multi-victim accidents create claims that require careful, strategic handling. A Fall River personal injury attorney managing a case where multiple parties were injured will coordinate the claims process to protect your share of available coverage and pursue every other source of compensation that might be available.
The Insurance Minimum Change and Uninsured Motorist Coverage
Massachusetts has long required drivers to carry uninsured motorist coverage. The new minimum for that coverage also increased to $25,000 per person and $50,000 per accident, matching the new liability minimums. This is meaningful for hit and run victims and for people injured by drivers who carry no insurance despite the legal requirement.
If you’ve been in an accident since July 1, 2025, the coverage analysis in your case should be based on the current minimums, not the old ones. A personal injury lawyer in Fall River will run that analysis correctly from the start and identify every applicable policy.
Older Accidents Have Different Coverage Baselines
The July 2025 minimum change only applies to policies renewed or issued after the effective date. Policies in force before July 1 continue under their existing terms until renewal. This means that accidents that happened in 2024 or early 2025 may still involve policies with the old $20,000 minimums, even if you’re still pursuing a claim now.
Your attorney will identify the correct coverage terms for the specific policy in effect at the time of your accident. This is a routine part of the coverage analysis in any motor vehicle claim, and it determines the baseline from which all other calculations proceed.
Understanding Your Own Coverage Is Part of Being Prepared
One practical takeaway from all of this is that reviewing your own auto insurance policy is something every Massachusetts driver should do periodically. Know what liability limits you carry. Know whether you have UIM coverage and at what limits. Know your PIP coverage. The decisions you make about your own policy before an accident happen determine the resources available to you if something goes wrong on the road.
If you’ve already been hurt in an accident in Fall River and you’re trying to understand what coverage is available to you, a free consultation with a Fall River personal injury attorney is the clearest way to get that picture. It costs nothing and takes the guesswork out of a process that can otherwise be genuinely confusing.