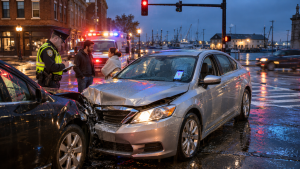
 Take one intersection, one wet evening and one silver sedan with a rideshare app open on the dashboard. Now imagine the same collision happening at three different moments of the driver’s night. The impact is identical, the injuries are identical, and yet the insurance behind the sedan is not. That quirk is the reason people who are hurt in these crashes so often feel lost. We will walk through the three moments in turn, because the best way to understand a New Bedford rideshare accident lawyer’s first questions is to see why the timing matters so much.
Moment one: the driver is online but has no ride
Our driver, whom we will call Omar, has just logged in and is circling downtown, waiting for the phone to buzz. Nobody is in the car. If he slides through a red light now, the state treats him as being in the first of three stages.
Massachusetts publishes a yearly report on rideshare companies, and the 2023 edition lays out what is required at each stage. For this one, a driver must carry liability coverage of at least $50,000 for any single injured person, $100,000 for all injured people in the crash, and $30,000 for damaged property. Medical payments under personal injury protection are listed at $8,000 per person.
The report also says the rideshare company answers for losses in this stage when Omar’s own auto policy does not respond. It points out that ordinary personal policies often exclude this kind of use, though some insurers sell an add-on to cover it. For an injured person, that can mean several insurers, each reading the policy language and suggesting the claim belongs to somebody else.
Moment two: the ride has been accepted
A minute later the phone buzzes. Omar taps accept and starts driving toward the pickup address. The rider is still on the sidewalk, but a trip now exists. If the crash happens here, the state treats him as being in the second stage, and the numbers change sharply. According to the same report, liability coverage for injury and property damage rises to $1,000,000 per crash, with the same $8,000 in medical payments.
That is a very different amount from the first stage. Whoever Omar hits at this point, whether a driver, a cyclist or a pedestrian, is dealing with the larger policy. The jump is also why insurers dig harder into the details of what happened.
Moment three: a rider is in the car
Finally, Omar picks up a passenger named Elena and heads across the city. The report treats the stretch from pickup until she gets out as the third stage, and it carries the same $1,000,000 limit and the same $8,000 in medical payments. The report explains that the chance of a passenger being hurt is part of the reason the higher limit applies to these last two stages and not to the first.
If Elena is injured, she is exactly the person that limit was designed for. If a driver in another car is hurt, that limit is again what stands behind Omar.
Why a higher limit is not the same as an easy claim
A bigger policy does not make anyone pay faster. A claim worth more draws more scrutiny: medical records are read line by line, and recorded statements get replayed. Insurers may also argue about which moment the crash fell into, because it changes who pays. If Omar’s app shows a trip request that was accepted seconds before impact, that timestamp matters. If he says he had just ended a ride, that matters too.
Gathering proof of the moment
Because the stage controls the coverage, the first priority after a crash is evidence of what the driver was doing. As a passenger, take screenshots of the trip screen and the driver’s profile right away, and keep the emailed receipt, which usually shows times and a route. If you were in another car or on foot, ask the driver straight out whether a trip was active, and write down the answer along with the time. Photograph the vehicle, including any rideshare sticker or illuminated sign. Ask the police to mention the rideshare connection in their report.
Seeing a doctor and why it matters
Get examined soon, even if all you feel is stiffness. A record made within a day or two ties your symptoms to the crash. Describe the impact clearly to the provider, because the way the injury is first written down tends to follow the claim from then on.
Shared blame still applies
Insurance limits describe the money available, not who deserves it. Under the comparative negligence statute, G.L. c. 231, section 85, a person found more than half responsible cannot recover, while a person with a smaller share has their recovery reduced by that share. Passengers are rarely at fault, but questions about seat belts or distracting the driver can still come up, and drivers of other cars are often blamed first by whichever insurer calls. Keep your account factual and consistent.
Small decisions that cause big problems
A few choices come up again and again. People accept an early settlement offer before they know how long treatment will last. They give recorded statements to adjusters without preparing. They post about the crash on social media. Some accept a credit from the app and assume the matter is closed, when a credit is a gesture and not a resolution of an injury claim. Pause before agreeing to anything that has conditions attached.
When to bring in a lawyer
You do not need a perfect file to ask for advice. A free consultation can help you work out which stage applied, which insurers are involved and what needs to be preserved. Bring your receipt, the police report, your medical papers and your photos. Because trip data can be replaced or overwritten over time, starting early gives a New Bedford rideshare accident lawyer the best chance of capturing it.